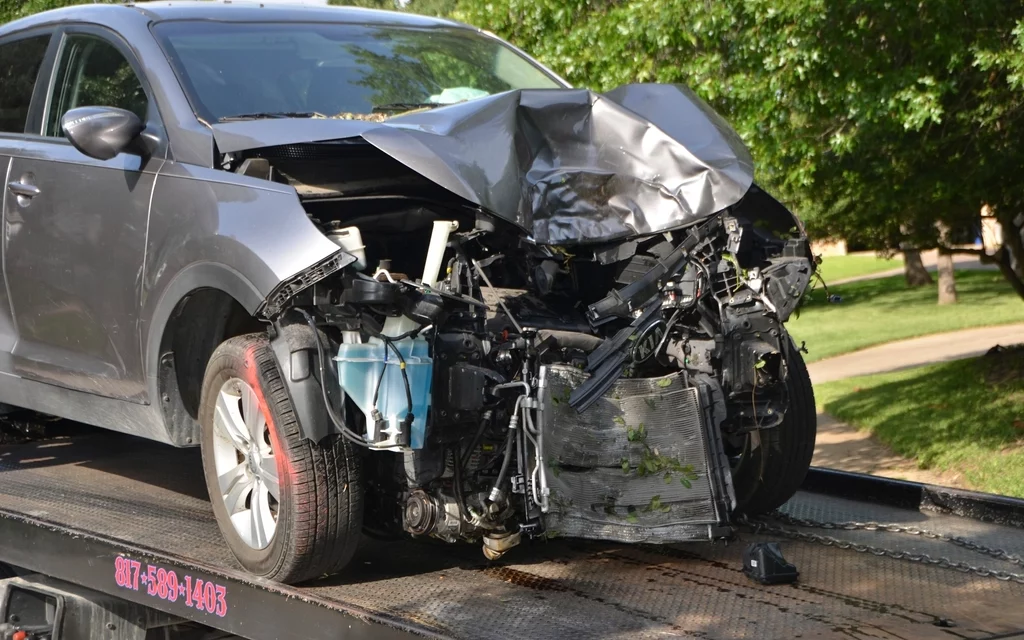
After an accident, the practical question arrives quickly: should you use the bodyshop your insurer has nominated, or take the car to a garage you already trust? The answer is not simply that you must accept the insurer’s choice, nor that you can switch repairer with no consequences.
It depends on the wording of your policy, the type of claim and, crucially, what the insurer agrees before work begins. Choosing the right route can affect the repair guarantee, a courtesy car, any excess, and who must put things right if the repair is poor.
Can an insurer make you use its approved repairer?
An insurer can set out a preferred or approved repair network in its policy and claims process. For a comprehensive claim, it will commonly arrange and pay for the repairs through that network. But a policyholder can ask to use a different repairer. The important point is to get the insurer’s position in writing before authorising any work.
Do not assume the insurer will pay an independent garage’s estimate in full, accept its labour rate, provide a replacement car, or take responsibility for its workmanship. Some policies limit particular benefits if you choose a non-approved repairer. Others will agree to the choice, but only on defined terms.
Ask the claims handler: Will you authorise this garage? What amount have you approved? Who guarantees the repair? What happens to my courtesy-car cover? Will I pay anything beyond my policy excess? Record the handler’s name, the date and the claim reference.
Why an approved repairer can be the lower-risk option
An approved repairer is not automatically the best bodyshop for every car, but it creates a clearer line of responsibility. The Financial Ombudsman Service says that where an insurer directs a customer to a garage, the insurer is responsible if something goes wrong with the repair. That matters if work is delayed, panels do not match, additional damage appears or the repair has not addressed all accident damage.
There may also be practical advantages: the insurer and repairer can deal directly with estimates and supplements, the excess may be collected at the end, and any replacement-vehicle arrangement is more likely to run through the claim. These are policy-specific benefits, not promises to rely on without checking.
When using your own garage may make sense
A preferred independent bodyshop can be a sensible choice where it knows a specialist vehicle, has already inspected the damage, is manufacturer-approved, or is simply more convenient. It may also be attractive when you have a classic, a prestige car or a vehicle with particular paint, trim or calibration requirements.
Before agreeing, give the insurer the garage’s written estimate, contact details and proposed repair method. Ask whether it will inspect the car or require photographs first. If the estimate changes after strip-down, the garage should seek authority before carrying out additional chargeable work. A verbal agreement is not enough for an expensive repair.
The trade-off many drivers miss
If you arrange repairs at your own garage with the insurer’s agreement, responsibility for bad workmanship can shift. The Financial Ombudsman Service says it would not usually hold the insurer responsible for problems with a customer-chosen repairer, provided the insurer made that consequence clear. In that situation, your complaint about the repair itself may be with the garage rather than the insurer.
That does not mean an insurer can be vague. Keep the email or letter that sets out the arrangement. Check whether the garage offers its own written workmanship guarantee and whether it covers paint, parts, corrosion and any work subcontracted to another business.
What to check before you choose
- Policy wording: look for approved repairer, repair guarantee, courtesy car, excess and contribution clauses.
- Authorisation: ask the insurer to confirm the repairer and approved estimate in writing before work starts.
- Repair capability: for ADAS-equipped cars, ask how camera or radar calibration will be handled after bumper, windscreen or suspension work.
- Parts: ask whether the estimate uses new, recycled, pattern or manufacturer parts, and whether your policy permits them.
- Courtesy transport: do not assume it will be like-for-like. Check the vehicle class, fuel, insurance excess, mileage limit and collection date.
- Timescale: ask what parts are awaited and when the garage expects to begin. Keep any update that changes the promised date.
- Paper trail: save photographs of the damage, estimates, authority emails, invoices and collection paperwork.
Do not authorise a cash settlement blindly
An insurer may offer cash in lieu instead of managing a repair. It can be useful if you have a trusted garage or prefer not to make a claim-managed booking, but check the figure carefully. Find out whether it is inclusive of VAT, whether it includes likely hidden damage, and whether accepting it closes the claim. Once you take over the repair, the insurer may no longer manage delays or quality issues.
If the damage could affect roadworthiness, do not drive the car merely because a payment has been offered. Follow the recovery or inspection advice given for the vehicle’s condition.
If the repair is delayed or not good enough
Raise the issue with the insurer promptly, even if the work was carried out at an approved garage. Send clear photographs, the repair invoice, the collection report and a short timeline of what happened. Give the insurer a chance to inspect the vehicle and propose a remedy before commissioning corrective work yourself, unless safety makes that impossible.
The Financial Ombudsman Service lists delays, poor-quality work, additional damage, incomplete repairs, missing repair guarantees and replacement-vehicle disputes among the motor-repair complaints it considers. It says evidence such as repair history and engineers’ reports can be important. For a disputed technical issue, an independent engineer’s report can therefore be more useful than a long exchange of emails.
If the insurer’s final response does not resolve the issue, or it has not issued one within eight weeks of your formal complaint, you can take the matter to the Financial Ombudsman Service’s vehicle-repairs process. The service is free for consumers. Keep the complaint focused on the policy, the approval given, the evidence of the fault and the outcome you want.
The practical answer
You do not have to treat the insurer’s nominated repairer as the only possible choice. But the safest route is to compare the two options before authorising work, then get every important term confirmed in writing. An approved repairer can leave the insurer clearly accountable. Your own garage can be the better fit, but only if you understand who will stand behind the work, what the insurer has agreed to pay and which benefits may change.